
Call coverage obligations frequently give rise to disputes that materially affect a physician assistant’s compensation, liability exposure, and professional mobility. We have reviewed hundreds of PA employment and independent contractor agreements and regularly encounter employer-favorable language that creates ambiguity about when on-call duty attaches, how call pay is calculated, who provides malpractice protection and tail coverage, and what happens when coverage is reassigned or backfilled. This article explains the mechanics behind PA call coverage disputes, identifies common triggers, and details the contractual provisions that should be reviewed for financial and regulatory risk. Understanding these clauses before signing can help a PA identify unclear expectations, avoid preventable pay disputes, and evaluate whether the agreement adequately protects the PA’s license, income, and long-term flexibility.
What Is a PA Call Coverage Dispute?
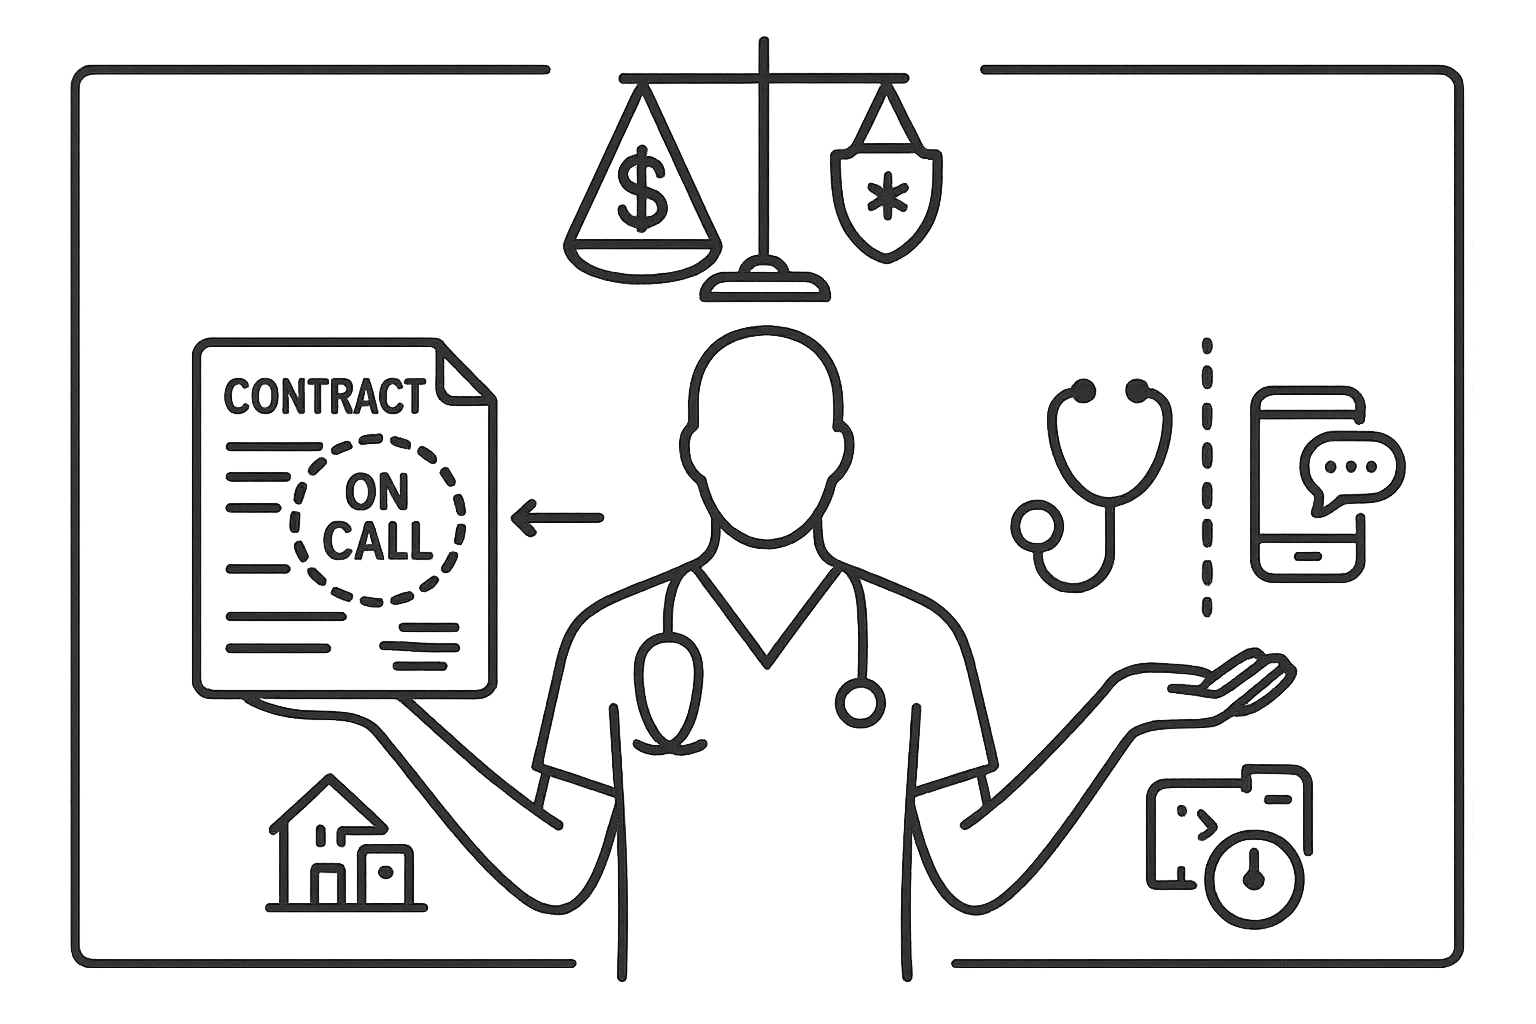
A call coverage dispute arises when the parties disagree about the existence, scope, compensation, or liability associated with on-call obligations. The disagreement may involve whether a particular period qualifies as call, which provider must respond, whether remote triage or in-person attendance is required, and how the PA receives credit for the work. These issues are easier to evaluate when the agreement clearly addresses the PA’s call schedule and coverage requirements.
- Whether a particular period qualifies as “on call” under the agreement
- Which provider must respond or furnish in-person coverage rather than remote triage
- How and when call stipends, premiums, productivity credit, or other compensation is earned
- Who bears malpractice exposure and any post-termination tail insurance obligation
- Whether the employer may rotate, reassign, or backfill call without adjusting compensation
Many disputes trace back to undefined terms, vague scheduling clauses, or reconciliation provisions that shift economic risk to the PA. A single unclear phrase such as “on call,” “available,” or “coverage window” can produce several downstream disagreements about response times, pay, clinical duties, and liability.
Why Call Coverage Terms Matter to Physician Assistants
Call coverage is not merely an operational scheduling issue. It can affect compensation, compliance, malpractice exposure, and a PA’s ability to move to another position. For PAs paid through collections, RVUs, or another production model, call-generated work may be excluded, delayed, or credited differently from regular clinical services. A focused review of compensation and productivity terms can identify whether the formula gives appropriate credit for call work.
- Financial impact: Delayed call pay, chargebacks, recoverable draws, or reconciliation adjustments can reduce take-home income and create unexpected repayment demands.
- Compliance risk: Call assignments must remain consistent with applicable scope-of-practice, supervision, delegation, prescribing, credentialing, and facility requirements.
- Insurance exposure: A PA may face an uninsured period or a substantial tail obligation if the agreement does not clearly allocate malpractice responsibilities.
- Professional mobility: Termination, noncompetition, nonsolicitation, and post-employment provisions may affect what happens after a call-related disagreement ends the relationship.
These consequences make call language an important part of the agreement’s overall risk profile. The provisions should be read together rather than treating the schedule, compensation formula, insurance terms, and termination section as unrelated clauses.
Common Causes of PA Call Coverage Disputes
Undefined Coverage Windows, Scheduling, and Backfill Duties
Disputes commonly arise when an agreement does not distinguish between remaining available by telephone, responding within a stated period, traveling to a facility, and remaining physically present for overnight coverage. The contract should address response expectations, the locations covered, the types of services required, and whether the PA must remain within a particular geographic area.
Backfill obligations can create a separate problem. Language allowing unilateral schedule changes or requiring a PA to cover an absent colleague may result in additional shifts without corresponding compensation or relief. Written procedures for schedule changes, replacement coverage, and coverage credit reduce the risk that duties will be reassigned retroactively.
Call Pay, Productivity Credit, and Reconciliation Conflicts
Call pay may take the form of a flat stipend, hourly premium, shift differential, per-encounter payment, RVU credit, or percentage of collections. Each model has different timing and reconciliation consequences. A stipend may provide predictability, while collections-based compensation can expose the PA to billing delays and collection risk. Under an RVU model, the agreement should explain which call services generate credit, the applicable conversion factor, and when the work appears in productivity reports.
Recoverable draws and post-period adjustments can intensify these disputes. If fluctuating call volume affects bonus calculations, the PA should understand the reconciliation period, the employer’s audit rights, and whether a shortfall may be deducted from future compensation or final pay. Agreements using this structure should also be reviewed for negative accrual terms that may carry a deficit from one measurement period to the next.
Supervision, Credentialing, and Malpractice Conflicts
Coverage obligations must align with the PA’s applicable state practice requirements and the facility’s credentialing limitations. A disagreement may arise when an employer expects independent decision-making or procedures that require physician involvement, additional privileges, or operational support that is not available during the coverage period. The agreement should not promise broader authority than the PA may lawfully and practically exercise.
Malpractice disputes often emerge when the contract does not identify the applicable policy type, covered duties, or responsibility for post-employment protection. Under a claims-made policy, tail coverage may be required for claims reported after the underlying policy ends. A PA should therefore examine the agreement’s tail insurance obligations, including whether the employer or PA bears the cost after termination.
Contract Provisions That Should Be Reviewed
A call coverage review should evaluate the provisions that determine when duties attach, how work is measured, and which party bears the associated financial and legal risks. Important terms include:
- Definitions: Clear meanings for “on call,” “coverage window,” “respond,” “remote triage,” and “in-person coverage.”
- Schedule and backfill authority: Limits on unilateral reassignment, mandatory replacement coverage, and changes to the call rotation.
- Compensation mechanics: The stipend, premium, encounter payment, RVU credit, collections percentage, or other formula used for call work.
- Reconciliation and audit rights: The timing of reports, correction procedures, chargebacks, draw recovery, negative accrual, and access to supporting records.
- Malpractice protection: The policy type, covered activities, premium responsibility, and allocation of any tail cost.
- Supervision and delegation: The physician availability, credentialing, and operational support necessary for the assigned duties.
- Termination and notice: Whether call duties and pay continue during a notice period and how final compensation is reconciled.
- Restrictive covenants: Whether a dispute or termination activates noncompetition, nonsolicitation, confidentiality, or other post-employment restrictions.
The termination section deserves particular attention because an unresolved coverage disagreement can become a resignation, discharge, or repayment dispute. A review of the termination provisions can clarify notice requirements, final-pay calculations, continuing call duties, and the effect of ending the relationship. The agreement’s restrictive covenant language should also be evaluated for limits that may apply after departure.
How to Reduce the Risk of a Call Coverage Dispute
Potential disputes are easier to address before the agreement is signed or before an informal scheduling practice becomes established. Contract-level definitions should state when call begins and ends, what response is required, which locations and services are covered, and how replacement assignments are handled. Compensation language should provide a formula that can be tested against low, average, and high call volumes rather than relying on a vague promise of additional pay.
- Define compensable call activities and the applicable payment or productivity credit.
- Specify reporting, payment, and reconciliation deadlines.
- Place reasonable limits on clawbacks, recoverable draws, and retroactive adjustments.
- Confirm that required physician support and facility privileges will be available during coverage.
- Identify the malpractice policy type and expressly allocate tail responsibility.
- Require written procedures for schedule changes, backfill assignments, and disputed coverage credit.
Documentation is also important after employment begins. PAs should retain applicable schedules, assignment notices, call logs, productivity reports, and written communications about coverage changes. Consistent records can help verify the work performed, support a compensation claim, and respond to a retrospective audit or chargeback.
What to Do When a Call Coverage Dispute Arises
When a dispute develops, preserve the relevant agreement, amendments, schedules, emails, text messages, voicemail records, call logs, payroll records, and productivity reports. Compare the documented coverage activity with the contract’s definitions and compensation formula. If collections or RVUs determine pay, identify whether the issue involves delayed posting, excluded services, an incorrect conversion factor, or a reconciliation method that differs from the written agreement.
- Assess the immediate obligation: Determine what the agreement requires while the dispute remains unresolved.
- Audit compensation: Compare call activity with payroll, encounter, collections, and productivity records.
- Confirm insurance protection: Verify whether the carrier recognizes coverage for the dates and duties involved.
- Use appropriate internal channels: Document communications with HR, medical leadership, payroll, or practice administration.
- Evaluate termination consequences: Review notice, repayment, final-pay, malpractice, and restrictive covenant provisions before resigning or responding to threatened termination.
Legal review becomes especially important when the dispute involves substantial unpaid compensation, a threatened clawback, malpractice exposure, licensing concerns, or restrictions on future employment. A contract-centered assessment can identify the difference between the written obligations and the employer’s operational expectations while clarifying the financial and professional consequences of available options.
Frequently Asked Questions
What should a PA call coverage clause define?
The clause should define the coverage window, required response time, locations covered, remote and in-person duties, backfill responsibilities, documentation requirements, and compensation method. It should also identify any physician availability or credentialing support necessary for the PA to perform the assigned work.
Is a physician assistant automatically entitled to separate call pay?
Separate call compensation depends on the agreement, the employer’s pay structure, the duties performed, and any applicable legal requirements. The contract may use a stipend, premium, per-encounter payment, productivity credit, or a salary intended to include specified call obligations.
How can call coverage affect PA productivity compensation?
Call-generated work may receive RVU credit, enter a collections pool, qualify for a separate payment, or receive no additional credit under the written formula. Reporting delays, excluded services, chargebacks, and negative accrual provisions can also change the amount and timing of compensation.
Who pays for tail insurance after a call coverage dispute ends employment?
Responsibility depends on the malpractice policy and the employment agreement. If the PA is covered under a claims-made policy, the contract should explain whether the employer or PA must obtain and pay for tail coverage after termination.
Can an employer require a PA to backfill another provider’s call shift?
The answer depends on the scheduling, reassignment, and coverage provisions in the agreement. The contract should clarify the employer’s authority to change the rotation, any limits on additional assignments, the notice required, and whether the PA receives additional pay or coverage credit.
When should a PA seek legal review of a call coverage dispute?
Legal review is particularly important when the disagreement involves substantial unpaid compensation, a repayment demand, threatened termination, malpractice exposure, licensing concerns, or a restrictive covenant. Early review can clarify the contract before the PA takes an action that affects notice obligations or post-employment rights.
Get Help Reviewing PA Call Coverage Terms
Chelle Law can review call schedules, compensation formulas, malpractice obligations, termination provisions, and other contract terms that may affect your income, license, and professional flexibility.
Contact Chelle Law