
Choosing between W-2 employment and 1099 independent contractor status is one of the most important structural decisions a physician assistant may face when evaluating a job offer. W-2 physician assistants are employees whose employers withhold taxes and may provide health insurance, retirement contributions, paid leave, and malpractice coverage. In contrast, 1099 physician assistants are treated as self-employed contractors who generally must manage their own taxes, insurance, benefits, and business expenses.
The distinction affects more than the compensation stated in an offer. Classification influences payroll taxes, income predictability, professional liability, workplace protections, termination rights, and post-employment restrictions. This guide explains how the two arrangements differ and which contract provisions can turn a higher stated rate into either a valuable opportunity or an unexpected financial risk. Both the written agreement and the practical working relationship should be evaluated before a PA signs an employment agreement or independent contractor contract.
How W-2 and 1099 Classification Works for Physician Assistants
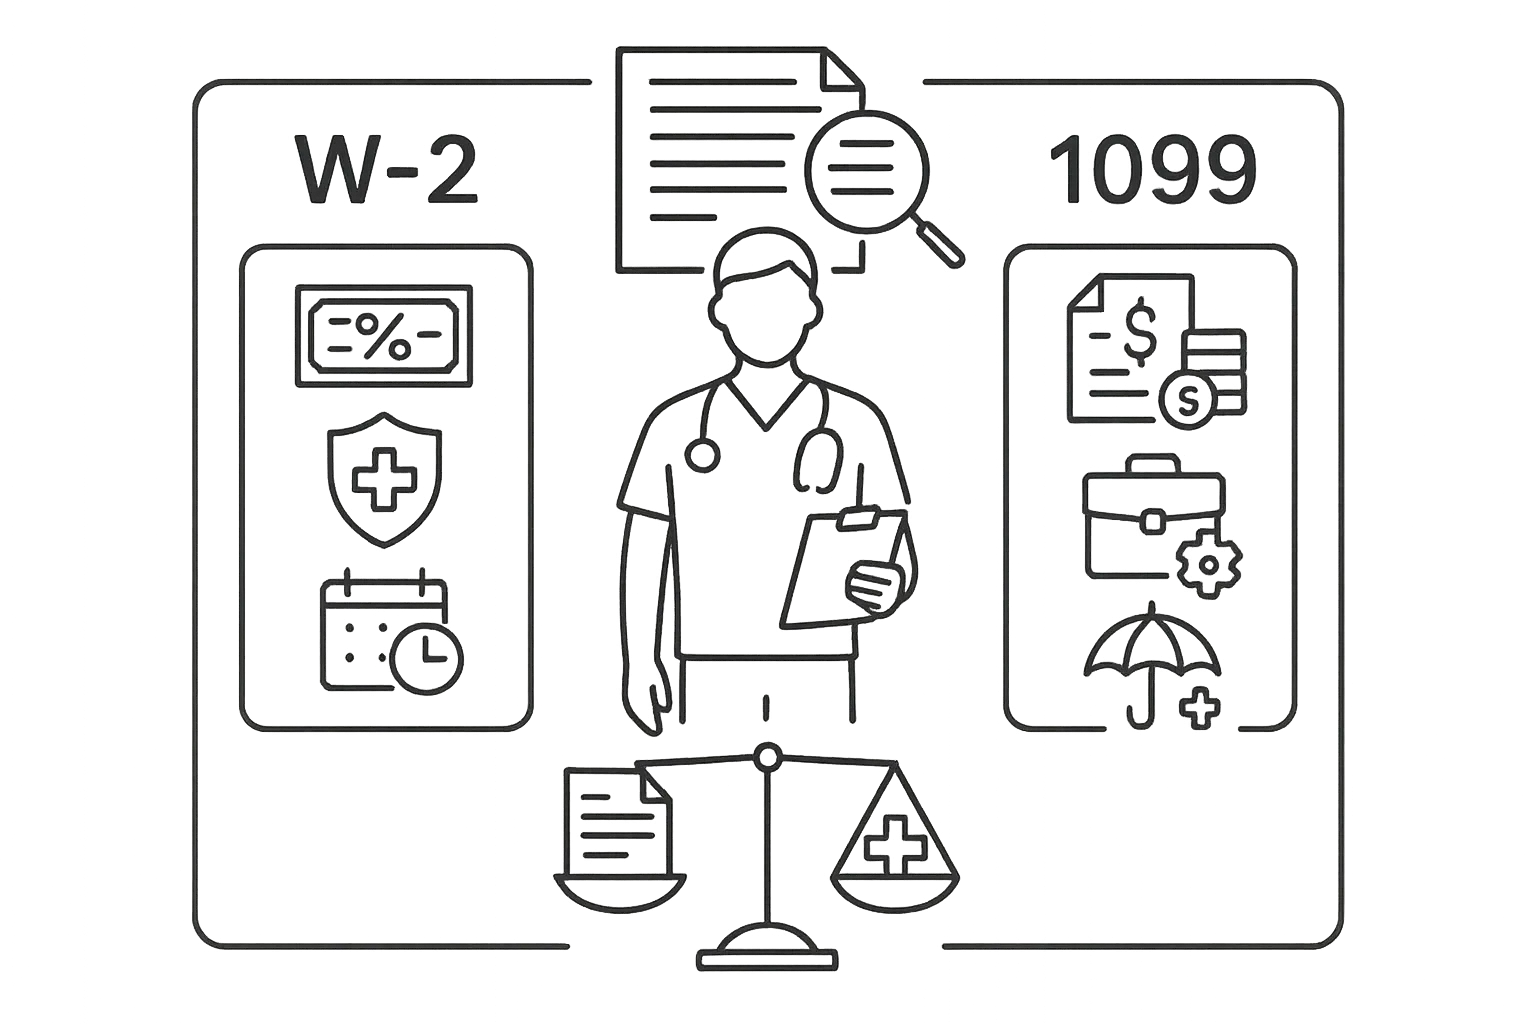
Employment classification determines which legal and tax framework governs the relationship between a physician assistant and the hiring entity. A W-2 employee is generally subject to employer payroll withholding, may receive employer-sponsored benefits, and may be covered by employment protections that apply to employees. A 1099 independent contractor is treated as self-employed for tax purposes and is ordinarily responsible for self-employment taxes, business expenses, personal benefits, and any insurance obligations assigned by the agreement.
The contract label does not necessarily resolve how the relationship operates. Payment structure, control over scheduling, supervision requirements, clinical protocols, exclusivity, insurance obligations, and termination mechanics can all be relevant. An agreement may call a PA an independent contractor while imposing strict scheduling, detailed operational control, or other employee-like obligations. The written terms and day-to-day arrangement therefore should be considered together.
Classification also affects unemployment coverage, workers’ compensation, malpractice responsibility, reimbursement of professional expenses, and access to benefits. Misclassification may create retrospective tax and regulatory exposure. The IRS provides additional general guidance concerning independent contractor classification rules, but a PA’s specific contract must still be evaluated under the circumstances that govern the relationship.
Taxes, Compensation, and Benefits
Physician assistants should compare the complete economic value of competing offers rather than relying only on the stated salary or hourly rate. Tax treatment, unpaid administrative time, insurance premiums, retirement contributions, paid leave, professional expenses, and payment timing can substantially change the net value of an arrangement.
Tax Withholding, Business Expenses, and Take-Home Pay
In a W-2 arrangement, the employer withholds applicable income, Social Security, and Medicare taxes from each paycheck and pays the employer share of payroll taxes. The PA receives net pay after withholding, usually through a predictable payroll schedule. Employees commonly depend on employer reimbursement policies for expenses such as licensing, credentialing, continuing medical education, and professional dues.
A 1099 physician assistant generally must pay self-employment taxes, make estimated tax payments, maintain records, and cover unreimbursed business expenses. Independent contractors may be able to deduct qualifying ordinary and necessary business expenses and use retirement options such as a SEP-IRA or Solo 401(k), but those potential advantages must be weighed against the absence of employer contributions and benefits. Invoicing or collections-based payment terms may also produce less predictable cash flow than employee payroll.
Compensation formulas require particular attention. A contractor’s higher gross rate may not offset self-employment taxes, unpaid leave, insurance premiums, or delayed collections. PAs comparing salary, productivity, RVU, or collections-based offers may benefit from a focused review of compensation terms before deciding which structure provides the stronger overall package.
Health Coverage, Paid Leave, and Workplace Protections
W-2 physician assistants may receive health insurance, paid time off, parental leave, disability coverage, and access to an employer-sponsored retirement plan. Employer premium contributions and retirement matching can represent a substantial part of total compensation. Eligibility requirements, waiting periods, scheduled hours, and part-time classifications should be checked because they may limit benefits that appear to be included in an offer.
Independent contractors generally do not receive paid leave, employer health coverage, or employer retirement contributions unless the written agreement expressly provides otherwise. They also may not qualify for unemployment insurance or coverage under the hiring entity’s workers’ compensation policy. Vague references to future benefits, bonuses, or partnership opportunities do not provide the same certainty as defined written terms.
Malpractice Insurance and Contractual Liability
Professional liability exposure can differ significantly between employee and contractor arrangements. The contract should identify who provides malpractice insurance, the policy type and limits, whether the PA must maintain separate coverage, and who pays for protection after the relationship ends. These details should be reviewed alongside indemnification language and any provisions that shift third-party claims or regulatory costs to the PA.
Claims-Made Coverage, Occurrence Coverage, and Tail Insurance
Occurrence coverage generally applies to covered acts that happen during the policy period regardless of when a claim is filed. Claims-made coverage ordinarily requires the policy to be active when the claim is made. When claims-made coverage ends, extended reporting coverage—commonly called tail insurance—may be needed for later-reported claims arising from prior services.
Employers often provide malpractice coverage for W-2 PAs, but the agreement should still state the policy type, applicable limits, and responsibility for tail coverage. Contractor agreements more commonly require the PA to obtain personal coverage and may assign the PA the cost of tail insurance at termination. Because this can be a significant expense, PAs should carefully review both their malpractice insurance obligations and the agreement’s tail coverage provisions.
Indemnification and Uninsured Exposure
Indemnification clauses can expand liability beyond ordinary malpractice exposure. Some agreements require the PA to defend or indemnify the hiring entity against third-party claims, regulatory investigations, contractual disputes, or losses connected to the PA’s services. A broad obligation may extend beyond what professional liability insurance covers.
The provision should be evaluated to determine whether it is limited to the PA’s own negligent or wrongful conduct and whether it excludes employer negligence or matters outside the PA’s control. Contractor status should not be assumed to make every business or operational risk the PA’s responsibility.
Contract Terms That Can Change the Value of Either Arrangement
A physician assistant agreement may contain specialized provisions affecting supervision, scheduling, compensation, termination, and professional mobility. These clauses often matter as much as the classification itself because they determine how the relationship functions and what happens when it ends.
Payment Formulas, Termination, and Repayment Obligations
Compensation may consist of guaranteed salary, hourly pay, productivity bonuses, RVU compensation, collections-based formulas, or a draw subject to reconciliation. The agreement should explain when compensation is earned, how productivity is calculated, whether expenses or payer adjustments are deducted, and when final compensation is paid. Negative accrual or reconciliation language may permit a deficit to carry forward or become repayable.
Termination provisions should clearly address without-cause termination rights, required notice, for-cause events, final payment, and continuing obligations. Signing bonuses, relocation assistance, credentialing expenses, or training costs may become repayable when the relationship ends. A PA considering resignation or responding to employer action should review the contract’s termination and repayment terms before taking a step that could trigger avoidable liability.
Operational provisions also deserve attention. Scheduling requirements, call coverage, supervision obligations, documentation systems, billing rules, productivity expectations, exclusivity, and multi-site assignments may reveal how much control the hiring entity retains. Those terms can affect both classification analysis and the practical demands of the role.
Non-Competes and Other Post-Termination Restrictions
Non-compete clauses may restrict practice within a defined area and period, while non-solicitation provisions may limit contact with former patients, employees, colleagues, or referral sources. The practical effect depends on the restriction’s duration, geographic reach, covered services, and triggering events. Some provisions apply after resignation, termination without cause, or expiration of the agreement.
Even where enforceability depends on state law, broad language can create immediate obstacles to nearby employment, telehealth work, or locum assignments. A focused PA non-compete review can help identify how a restriction may affect future opportunities before the agreement is signed.
How to Compare a W-2 Offer With a 1099 Offer
The comparison should account for income predictability, tax responsibility, benefits, professional expenses, liability exposure, workplace protections, and post-termination mobility. A higher contractor rate is not automatically more valuable if the difference is absorbed by self-employment taxes, unpaid time off, health coverage, retirement contributions, malpractice premiums, or administrative work.
Before accepting either arrangement, consider the following questions:
- Does the stated classification match the hiring entity’s actual control over scheduling, supervision, clinical protocols, documentation, and billing?
- What is the net compensation after taxes, insurance, unpaid leave, retirement contributions, licensing fees, and other professional expenses?
- Who provides malpractice insurance, what type of policy applies, and who must pay for tail coverage?
- Can collections timing, reconciliation, negative accrual, or chargebacks delay or reduce payment?
- What notice, repayment, and final-compensation terms apply when the relationship ends?
- Could a non-compete, non-solicitation clause, or exclusivity provision limit future work?
A side-by-side financial comparison should assign a reasonable value to employer contributions and expenses the PA would assume as a contractor. Any uncertainty about payment formulas, insurance, classification, or termination should be resolved in writing rather than left to an informal explanation.
Transitioning Between Employee and Contractor Status
A transition between W-2 and 1099 status should be documented carefully so that compensation, taxes, insurance, and contractual responsibilities remain aligned. When leaving an existing arrangement, the PA should obtain written confirmation of the termination date, final compensation, outstanding bonus or expense obligations, and responsibility for malpractice tail coverage.
A new contractor agreement should define invoicing procedures, payment deadlines, professional expense reimbursement, insurance requirements, scheduling expectations, and termination rights. A PA moving into employee status should confirm the payroll start date, benefit eligibility, treatment of existing productivity compensation, and whether prior contractor receivables will be paid separately. Addressing these issues in writing can reduce later disputes over compensation or coverage.
Frequently Asked Questions
Is a higher 1099 pay rate always better than a W-2 salary?
No. A contractor may need to pay self-employment taxes, obtain insurance, fund retirement, cover unpaid leave, and absorb professional expenses. The stated rate should be compared with the complete value of a W-2 package and the contractor’s expected costs.
Can a physician assistant be called a contractor but function like an employee?
Yes. The contract label is only one part of the analysis. Scheduling control, supervision, exclusivity, clinical protocols, billing systems, and the practical working relationship may indicate employee-like control even when the agreement uses independent contractor language.
Who pays malpractice insurance for a 1099 physician assistant?
The contract should answer that question. Some hiring entities provide coverage, while other agreements require the PA to purchase and maintain a personal policy. The agreement should also identify policy limits, the coverage type, and responsibility for tail insurance.
Do independent contractor PAs receive health insurance or paid time off?
Independent contractors generally do not receive employer-sponsored health insurance or paid leave unless the written agreement expressly provides those benefits. The cost of replacing them should be included when comparing contractor compensation with a W-2 offer.
What termination terms should a PA review in a 1099 agreement?
The PA should review without-cause notice, for-cause events, final payment timing, outstanding receivables, tail insurance, and repayment obligations involving bonuses, relocation, training, or negative accrual balances.
Should a physician assistant have a W-2 or 1099 agreement reviewed before signing?
A review can help the PA understand classification language, compensation formulas, insurance duties, termination rights, restrictive covenants, and other provisions that may materially affect the arrangement’s financial value and professional risk.
Understand the Full Cost of Your PA Contract
Chelle Law reviews W-2 employment agreements and 1099 independent contractor contracts for compensation, insurance, termination, restrictive covenants, and other terms that can affect your financial and professional risk.
Contact Chelle LawExplore Physician Assistant Contract Guidance
Review legal services, practical resources, and state-specific information for physician assistant agreements.