

Relief, or locum, veterinarians provide temporary clinical coverage for vacations, caseload spikes, leave periods, and short-term staffing gaps. Many practices engage these veterinarians as independent contractors rather than employees. A contractor arrangement can offer flexibility, but the agreement must accurately define the working relationship, compensation method, professional responsibilities, and expenses allocated to each party.
The independent contractor label also carries meaningful legal, financial, and professional risks. A veterinarian may face inconsistent payment calculations, unexpected tax obligations, malpractice coverage gaps, restrictive covenants, cancellation losses, or classification concerns if the practice controls the work like an employer. These issues become especially important when the veterinarian works at multiple clinics, receives production-based compensation, or accepts assignments through a corporate veterinary group.
Chelle Law reviews relief veterinarian agreements to identify how the contract addresses contractor status, compensation, malpractice insurance, tail coverage, scheduling control, termination, indemnification, and post-contract restrictions. Understanding those provisions before signing can help a relief veterinarian protect income, preserve professional mobility, and avoid accepting obligations that do not match the practical working arrangement.
Key Takeaways for Relief Veterinarians
- Require a clear compensation formula that defines collections or production, payment timing, reconciliation procedures, and any limits on clawbacks.
- Confirm who provides malpractice coverage, whether the policy is claims-made or occurrence, and who is responsible for tail insurance when required.
- Preserve meaningful independence by retaining the ability to accept or decline assignments and avoiding contract terms that impose employee-like control.
- Review noncompete and non-solicitation provisions under the law of the state where the veterinarian will work, and negotiate narrow limits or removal where appropriate.
- Consider an attorney-led review when compensation is production-based, insurance obligations are unclear, the agreement covers multiple locations, or the practice shifts broad liability to the veterinarian.
Relief Veterinarian Contractor Status and the Working Relationship
A relief veterinarian independent contractor is a clinician hired temporarily to provide patient care, usually under an agreement specifying dates, daily or per-shift rates, and the scope of clinical duties. Unlike associates on payroll, relief contractors generally invoice the clinic, do not receive payroll tax withholding, and may be responsible for their own benefits, licensing expenses, business costs, and professional liability insurance. Veterinarians comparing these arrangements should understand the practical differences between W-2 employment and 1099 contractor status.
The contract label is not the only consideration. Tax agencies, labor authorities, and courts may examine the actual working relationship, including who controls the schedule, whether the veterinarian can decline assignments, how closely the veterinarian is integrated into the practice, and who provides tools or pays business expenses. Even when an agreement calls the veterinarian an independent contractor, day-to-day requirements may create exposure if the relationship functions more like employment.
State law can affect worker classification and the enforceability of contractual restrictions. Relief veterinarians should therefore review the rules where they will perform services rather than assuming one agreement works identically in every jurisdiction. A focused independent contractor agreement review can identify provisions that undermine contractor autonomy or transfer disproportionate financial and professional risk.
Compensation and Insurance Risks in Relief Agreements
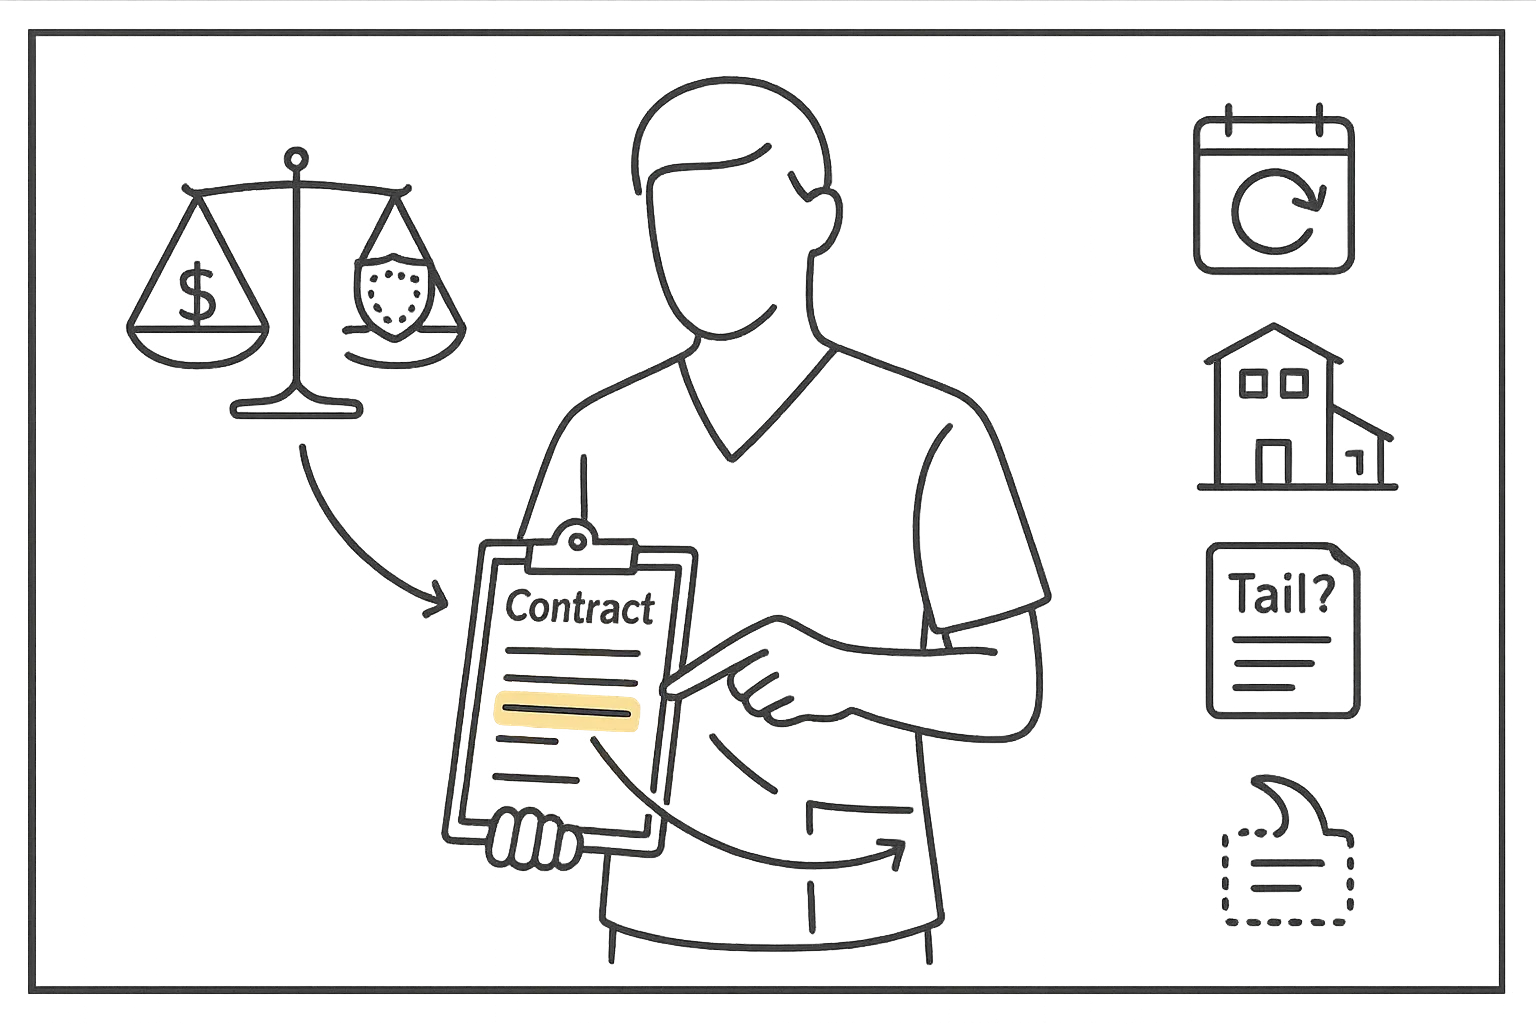
Relief agreements are often presented as simple short-term contracts, but compensation and insurance provisions can shift substantial risk to the veterinarian. The agreement should explain not only the stated rate but also how payment is calculated, when an invoice becomes payable, what insurance applies, and whether obligations continue after the assignment ends.
Compensation, Collections, and Clawback Provisions
Relief veterinarians may receive a flat daily or shift rate, a per-appointment amount, or a percentage of production or collections. Problems arise when the agreement does not define collections, distinguish gross receipts from net revenue after adjustments, or explain which services receive production credit. A sound formula should address calculation examples, invoice requirements, payment timing, reconciliation procedures, and access to supporting statements. Veterinarians offered percentage-based pay may benefit from a separate review of compensation and ProSal terms.
Production-based agreements may also impose negative accrual, retroactive adjustments, or repayment obligations if a scheduled block is canceled. Relief veterinarians should question provisions that carry a shortfall forward, permit unilateral deductions, or require repayment for circumstances outside their control. Negotiated protections may include caps, defined reconciliation periods, itemized statements, and exceptions for practice-initiated cancellations.
Compensation varies by region, practice type, schedule, and clinical setting. Emergency and specialty assignments may command higher rates, while rural work may include travel, lodging, or per diem benefits. Corporate groups may use standardized rates, whereas independent clinics may have more flexibility. Whatever the arrangement, the contract should specify the expected shift length, additional-hours compensation, cancellation fees, travel reimbursement, lodging, and the deadline for final payment.
Malpractice Coverage, Tail Insurance, and Multiple Locations
Professional liability insurance may be written on a claims-made or occurrence basis. Occurrence coverage generally responds to a covered event occurring during the policy period even if the claim is made later. Claims-made coverage may require continued coverage or tail protection after the underlying policy ends. The agreement should identify the policy type, coverage limits, named insureds, exclusions, and the party responsible for any required tail coverage. The distinctions are discussed further in the claims-made versus occurrence coverage guide.
If the clinic supplies coverage, the veterinarian should determine whether it applies to every assigned location and to mobile, emergency, or telemedicine services when relevant. If the veterinarian carries an individual policy, the contract should not create inconsistent or duplicative obligations without explaining how the policies coordinate. The veterinarian should also review whether the practice requires separate general business, cyber, or other liability coverage.
Insurance language should be reviewed together with indemnification provisions. Broad indemnity clauses can require a veterinarian to defend or reimburse the practice for claims extending beyond the veterinarian’s own conduct. Any indemnification obligation should be examined for scope, available insurance, procedural protections, and whether the practice assumes corresponding responsibility for its conduct, personnel, premises, and systems.
Tax, Labor, and Worker Misclassification Exposure
Worker misclassification can have tax, wage-and-hour, and unemployment insurance consequences. The applicable test may differ by jurisdiction and legal context, but control over the work is frequently important. Relief veterinarians should be cautious when an agreement describes an independent business relationship while requiring exclusivity, fixed recurring shifts, employee-style supervision, or extensive integration into the clinic’s operations.
Control Factors and Employee-Like Contract Terms
Factors that may be examined include who sets the veterinarian’s schedule, whether assignments may be accepted or declined, who supplies equipment and uniforms, how the veterinarian is presented to clients, and whether the practice controls the manner of performing day-to-day work. Regular staff meetings, clinic-specific email accounts, mandatory shift blocks, detailed performance rules, and placement on the practice’s employee roster may also be relevant depending on the governing test.
A classification dispute may lead to questions about payroll taxes, unemployment contributions, benefits, wage obligations, and penalties. Contract language alone cannot resolve every classification issue if the actual conduct of the parties points in another direction. The agreement and working practices should therefore be consistent, and the veterinarian should understand which obligations come with operating an independent business.
Practical protections may include a meaningful right to decline assignments, nonexclusive work, clearly defined onboarding, independent invoicing, and responsibility for genuine business expenses. Veterinarians should retain invoices, travel records, supply receipts, insurance documents, and other business records. These practices do not guarantee a particular legal classification, but they can help document how the parties structured and performed the relationship.
Noncompetes, Non-Solicitation, and Client Restrictions
Relief agreements may contain noncompete clauses, restrictions on soliciting clients or employees, confidentiality provisions, and limitations on future assignments. These clauses can quietly restrict where a veterinarian works after a short engagement. Enforceability varies by state, so a veterinarian should not assume a restriction is valid or invalid without reviewing the governing law and the specific language. The veterinary noncompete guide explains common issues affecting duration, geographic scope, and restricted activities.
Common problems include broad geographic areas, lengthy restricted periods, restrictions covering every location owned by a corporate group, and clauses prohibiting treatment of clients the relief veterinarian never served. Staff non-solicitation provisions can also prevent future assignments with regional practices or other businesses under shared ownership. When a restriction cannot be removed, possible revisions include narrowing it to clients personally treated, excluding pre-existing relationships, limiting the covered locations, and reducing its duration.
Relief work rarely includes an ownership pathway, but some practices use temporary assignments as a precursor to employment or partnership discussions. Any proposed buy-in should identify the valuation process, timeline, ownership percentage, voting rights, profit distributions, financing terms, and conditions that must be satisfied. A general reference to a future partnership opportunity is not a substitute for developed written terms.
Negotiating a Relief Veterinarian Agreement
A short-term agreement still deserves careful negotiation. The most useful revisions usually clarify economics, preserve appropriate contractor autonomy, allocate insurance responsibilities, and establish what happens when either party cancels or ends the relationship. Agreed changes and assurances should be placed in the signed contract or a written addendum rather than left as verbal promises.
Contract Terms to Request or Clarify
- Compensation: Define daily, hourly, production, or collections-based pay; include calculation examples; and specify invoicing, reconciliation, and payment deadlines.
- Malpractice coverage: Identify whether coverage is claims-made or occurrence, who pays premiums, and who purchases tail coverage when required.
- Cancellation and travel: Establish cancellation notice, cancellation fees, mileage, airfare, lodging, and meal reimbursement.
- Control and autonomy: Preserve the ability to accept or decline assignments and avoid unnecessary exclusivity or employee-like operational control.
- Restrictive covenants: Remove unnecessary restrictions or narrow their duration, geography, covered clinics, clients, and prohibited activities.
- Indemnity: Avoid provisions that make the veterinarian responsible for the practice’s negligence, personnel, facilities, billing systems, or other matters outside the veterinarian’s control.
- Termination: Define notice requirements, immediate-termination grounds, scheduled-shift obligations, access to records, and the deadline for final invoicing and payment.
Before signing, confirm that the payment method and timing are defined, malpractice and tail responsibilities are clear, travel and cancellation terms are included, and the agreement preserves a workable degree of independence. A relief veterinarian should also understand every repayment obligation and the consequences of ending the agreement before completing a scheduled assignment block.
When to Seek an Attorney-Led Contract Review
An attorney-led review is particularly useful when compensation depends on production or collections, the practice provides claims-made coverage without clear tail terms, the agreement contains restrictive covenants, the veterinarian will work at multiple locations, or a corporate agreement offers little room for negotiation. Other warning signs include unilateral pay adjustments, broad indemnification, long notice periods, automatic renewal, repayment obligations, and inconsistent language about contractor autonomy.
Attorney Robert Chelle and the Chelle Law team review veterinary contracts nationwide. The review explains how provisions affect compensation, mobility, liability, and the ability to end the relationship; identifies clauses that warrant clarification or revision; and proposes practical contract language when appropriate. Relief veterinarian agreements can be efficient and flexible, but the written terms should match the intended working relationship and protect the veterinarian from avoidable long-term exposure.
Frequently Asked Questions
What are the main independent contractor risks in a relief veterinarian agreement?
Common risks include worker misclassification, unclear compensation, negative accrual or clawbacks, malpractice coverage gaps, broad indemnification, and restrictive covenants. Each can affect taxes, income, liability, or future work, so the agreement should clearly address payment, insurance, autonomy, termination, and post-contract restrictions.
How can unclear collections or ProSal terms reduce a relief veterinarian’s pay?
Undefined collections or production terms may allow inconsistent credits, deductions, reconciliation adjustments, or negative accrual. The agreement should define the formula, identify included services and adjustments, provide calculation examples, establish access to statements, and specify when payment becomes due.
What malpractice and tail coverage terms should a relief veterinarian confirm?
The veterinarian should confirm whether coverage is claims-made or occurrence, the applicable limits and exclusions, every covered location, and who pays for tail coverage when required. The contract should also explain how practice-provided coverage coordinates with any individual policy carried by the veterinarian.
When might a relief veterinarian be treated as an employee instead of a contractor?
Classification risk may increase when a clinic controls recurring schedules, requires exclusivity, closely directs daily work, or integrates the veterinarian into employee systems. The governing legal test varies, and the actual working relationship matters in addition to the contract’s independent contractor label.
Can a relief agreement require tail insurance or bonus repayment?
An agreement may allocate tail insurance costs or impose repayment obligations, although enforceability depends on the contract and applicable law. Before signing, the veterinarian should negotiate clear amounts, limited repayment periods, appropriate caps, and exceptions for practice-initiated cancellations or other circumstances outside the veterinarian’s control.
What termination terms should a relief veterinarian review before accepting assignments?
Review the notice period, immediate-termination grounds, scheduled-shift obligations, cancellation fees, repayment provisions, final invoice deadline, and payment timing. The contract should also explain whether restrictive covenants, confidentiality, indemnification, or insurance obligations continue after termination.
Review Your Relief Veterinarian Agreement Before You Sign
Chelle Law can review your independent contractor agreement, explain its financial and professional risks, and identify practical revisions involving compensation, insurance, termination, and restrictive covenants.
Contact Chelle Law